ચાલતી પટ્ટી
5 January 2023
25 December 2019
10 October 2018
FOR BC AND CSP
किसी भी बैंक का BC या CSP बनना चाहते हैं तो ये 6 Company पूरी India में BC और CSP दे सकती है 🔥🔥
UTL e Seva Website:- http://www.utleseva.com/
FIA Technology Services website:- https://www.fiaglobal.com/
Oxigen website link:- http://www.myoxigen.com/financial-ser...
Aisect Website Link:- http://www.aisect.org/
Zero Mass Website Link:- http://kioskbankingzmf.weebly.com/abo...
Aisect CSP apply Link:- http://www.aisectonline.com/Kiosk/Kio...
NICT Compay website Link:- http://www.nict.co.in/index.html
CSC NEWSLETTER LINK 31 JULY:- https://csc.gov.in/new_newsletter/201...
3 October 2018
Jeevan Shanti Surrender Value Calculator
https://www.insurance21.in/surrender-value-calculator/lic-jeevan-shanti-850.html
In LIC Jeevan Shanti plan (Plan 850), only options "F" & "J" under immediate annuity and both options available under deferred annuity can be surrendered after 3 months of purchase. Following calculator provides surrender value for above 4 options which are eligible for surrender value. Please note, it is not official surrender value calculator of LIC. The surrender value is based on various surrender factors applicable to those policies which will come for surrender before April-2019. These factors will be declared for each subsequent year in the future. The method of calculation is explained after the calculator.
1. During deferment period under Deferred Annuity:
Surrender Value = F3 * (F1 * Equivalent annuity amount payable for yearly mode + F2 * 110% of Purchase Price)
Where F1 and F2 are the Annuity Factor and Risk Factor respectively applicable at the age when annuity will start and F3 is the factor applicable for the outstanding deferment period in complete full years as at the date of surrender.
2. After deferment period under Deferred Annuity and Under Immediate Annuity:
Surrender Value = (F1 * Equivalent annuity amount payable for yearly mode + F2 * 110% of Purchase Price) - Annuity installments paid under the policy during the policy year of surrender up to the date of surrender
Where F1 and F2 are the Annuity Factor and Risk Factor respectively applicable at the age when policy is surrendered.
A policy with following details has been taken for explanation purpose.
As per above details, pension will start after 10 years when policy
holder's age will be 60 years. As the policy is surrendered after 20
years, so age of the policyholder at the time of surrender will be 70
years.
As per surrender factor circular for Jeevan Shanti policy, F1 and F2 will 7.3250 and 0.3091 respectively for surrender age 70 years. So calculation goes as follows.
Surrender Value= (7.3250 x 1,28,300 - 0.3091 x 1.1 x 10,00,000) - (1,28,300/2) =1215658
Assumptions: Annuity installments paid under the policy during the policy year of surrender up to the date of surrender is taken as half of yearly annuity (1,28,300/2). Years and ages are counted as whole years.
https://www.insurance21.in/surrender-value-calculator/lic-jeevan-shanti-850.html
In LIC Jeevan Shanti plan (Plan 850), only options "F" & "J" under immediate annuity and both options available under deferred annuity can be surrendered after 3 months of purchase. Following calculator provides surrender value for above 4 options which are eligible for surrender value. Please note, it is not official surrender value calculator of LIC. The surrender value is based on various surrender factors applicable to those policies which will come for surrender before April-2019. These factors will be declared for each subsequent year in the future. The method of calculation is explained after the calculator.
How to calculate surrender value in Jeevan Shanti Pension plan
Surrender Value in Jeevan shanty pension is calculated as per following formulas.1. During deferment period under Deferred Annuity:
Surrender Value = F3 * (F1 * Equivalent annuity amount payable for yearly mode + F2 * 110% of Purchase Price)
Where F1 and F2 are the Annuity Factor and Risk Factor respectively applicable at the age when annuity will start and F3 is the factor applicable for the outstanding deferment period in complete full years as at the date of surrender.
2. After deferment period under Deferred Annuity and Under Immediate Annuity:
Surrender Value = (F1 * Equivalent annuity amount payable for yearly mode + F2 * 110% of Purchase Price) - Annuity installments paid under the policy during the policy year of surrender up to the date of surrender
Where F1 and F2 are the Annuity Factor and Risk Factor respectively applicable at the age when policy is surrendered.
Example of calculation in case of "after deferment period under Deferred Annuity"
Advertisement
| Age at purchase | 50 |
| Purchase Price | 10,00,000 |
| Deferement Period (Years) | 10 |
| Purchase Year | 2018 |
| Surrender Year | 2038 |
| Annuity(Yearly) | 128300 |
As per surrender factor circular for Jeevan Shanti policy, F1 and F2 will 7.3250 and 0.3091 respectively for surrender age 70 years. So calculation goes as follows.
Surrender Value= (7.3250 x 1,28,300 - 0.3091 x 1.1 x 10,00,000) - (1,28,300/2) =1215658
Assumptions: Annuity installments paid under the policy during the policy year of surrender up to the date of surrender is taken as half of yearly annuity (1,28,300/2). Years and ages are counted as whole years.
JEEVAN SANTHI PENSION CALCULATOR
CLICK ON BELOW LINK TO CALCULATE THE PENSION AMOUNT
https://www.insurance21.in/pension-calculator/lic-jeevan-shanti-850.html
After payment of Rs. 2545000, the pension as per following table will start from 60 years of age and continue as long as Annuitant or Policyholder survives. Any of the four Pension Receiving Mode may be selected.
Following table provides policy year-wise death claim details as per above formula.
For calculation purpose, whole years have been considered, for
example, 1 year and 5 months are counted as 2 years. The GAs has been
added on yearly basis to simply the calculations.
The death claim amount will be paid to the nominee. However nominee will have the option to take death claim as lumpsum amount or in installments or in the form of annuity (pension). If nominee decides to take it as annuity, then it will be like, buying a new policy against death claim amount.
https://www.insurance21.in/pension-calculator/lic-jeevan-shanti-850.html
Annuity, Death Claim, Guaranteed Additions in LIC Jeevan Shanti
LIC Jeevan Shanti is a single premium guaranteed return annuity plan which has immediate and deferred annuity options. For purpose of explanation, suppose a 50 year person purchases deferred annuity option with 25 Lakh purchase price and 10 years deferment period. The pension and death claim for above policy has been explained below.
Annuity (Pension) Details
| Deposit Amount | GST | Final One Time Deposit |
|---|---|---|
| Rs. 2500000 | Rs. 45000 | Rs. 2545000 |
| Pension Mode | Amount |
|---|---|
| Yearly | 321625 |
| Half Yearly | 157533 |
| Quarterly | 77946 |
| Monthly | 25709 |
Advertisement
Death Claim Details - During Deferment Period
In case of death of policyholder(s) during deferment period (i.e. before 10 years), death claim shall be higher of following two values.- Purchase Price + Accumulated Guaranteed Additions (GAs), OR
- 110% of Purchase Price
Following table provides policy year-wise death claim details as per above formula.
| Policy Year | Age | Purchase Price | Guaranteed Additions | Death Claim |
|---|---|---|---|---|
| 1 | 51 | 2500000 | 302880 | 2802880 |
| 2 | 52 | 2500000 | 605760 | 3105760 |
| 3 | 53 | 2500000 | 908640 | 3408640 |
| 4 | 54 | 2500000 | 1211520 | 3711520 |
| 5 | 55 | 2500000 | 1514400 | 4014400 |
| 6 | 56 | 2500000 | 1817280 | 4317280 |
| 7 | 57 | 2500000 | 2120160 | 4620160 |
| 8 | 58 | 2500000 | 2423040 | 4923040 |
| 9 | 59 | 2500000 | 2725920 | 5225920 |
Death Claim Details - After Deferment Period
In case of death of policyholder after deferment period (i.e. after 10 years), death claim shall be higher of following two values.- Purchase Price + Accumulated Guaranteed Additions (GAs) - Total annuity payouts till date of death, OR
- 110% of Purchase Price
| Policy Year | Age | Purchase Price + Accumulated GA | Cumulative Annuity Paid | Death Claim |
|---|---|---|---|---|
| 10 | 60 | 5528800 | 321625 | 5207175 |
| 15 | 65 | 5528800 | 1929750 | 3599050 |
| 20 | 70 | 5528800 | 3537875 | 2750000 |
| 25 | 75 | 5528800 | 5146000 | 2750000 |
| 30 | 80 | 5528800 | 6754125 | 2750000 |
| 35 | 85 | 5528800 | 8362250 | 2750000 |
| 40 | 90 | 5528800 | 9970375 | 2750000 |
| 45 | 95 | 5528800 | 11578500 | 2750000 |
| 50 | 100 | 5528800 | 13186625 | 2750000 |
| 55 | 105 | 5528800 | 14794750 | 2750000 |
| 60 | 110 | 5528800 | 16402875 | 2750000 |
| 65 | 115 | 5528800 | 18011000 | 2750000 |
Please note, above calculations are for the purpose of explanation.
JEEVAN SANTHI
LIC Jeevan Shanti – Single Premium Guaranteed Pension Plan
Key Features- Single Premium Annuity Plan – Immediate or deferred annuity
- Guaranteed Annuity Rates at the inception of the policy for both annuity types
- Annuity Option fixed at the time of opting policy. No change in the selected option is allowed.
- 10 different immediate annuity options.
- Joint life annuity option available.

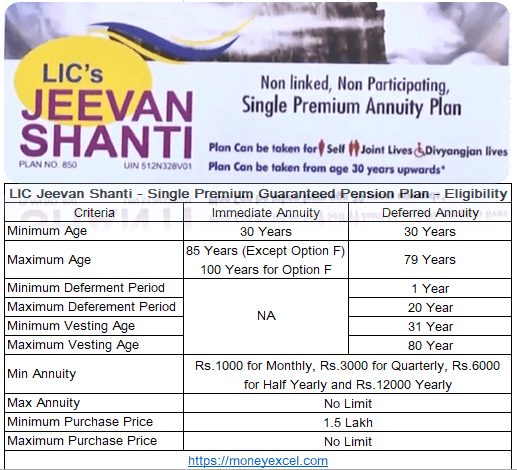
From above eligibility details it is clear that minimum purchase price for this policy is 1.5 Lakh and minimum annuity is Rs.1000 per month. (Rs.12000 yearly).
Annuity Options
- Option A Immediate Annuity for life
- Option B Immediate Annuity with a guaranteed period of 5 years and life thereafter
- Option C Immediate Annuity with a guaranteed period of 10 years and life thereafter
- Option D Immediate Annuity with a guaranteed period of 15 years and life thereafter
- Option E Immediate Annuity with a guaranteed period of 20 years and life thereafter
- Option F Immediate Annuity for life with return of Purchase Price
- Option G Immediate Annuity for life increasing at a simple rate of 3% p.a.
- Option H Joint Life Immediate Annuity for life with a provision for 50% of the annuity to the Secondary Annuitant on the death of the Primary Annuitant.
- Option I Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives.
- Option J Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives and return of Purchase Price on the death of the last survivor
- Option 1 Deferred annuity for Single Life at vesting age
- Option 2 Deferred annuity for Joint Life at vesting age
LIC Jeevan Shanti Plan – Benefits
Benefits of LIC Jeevan Shanti plan for immediate annuity.
Benefits payable on Survival
Annuity Option A to F – For Single Life – Annuity Payments in arrears as per the chosen mode of annuity.
Annuity Option G – For Single Life – Annuity Payments in arrears as per the chosen mode of annuity + Increase in annuity payment @3% per annum for every completed policy year.
Benefits payable on Death
Annuity Option A & G – Annuity Payment shall cease.
Annuity Option B to E – On death of annuitant during guaranteed period of 5/10/15/20 years, nominee receives annuity payments till expiry of guaranteed period.
Annuity Option F – Annuity Payment shall cease. Purchase price shall be payable to nominee.
Annuity Option H – On the death of the primary annuitant – 50% of the annuity amount to the surviving secondary annuitant till his/her survival.
Annuity Option I & J – 100% of the annuity amount shall continue to be paid as long as one annuitant is alive.
Benefits of LIC Jeevan Shanti plan for the Deferred annuity.
Benefits payable on Survival
Option 1 – No payment during deferment period. Annuity payments will be made in arrears to the Annuitant as per mode of annuity.
Option 2 – No payment during deferment period. Annuity payments will be made in arrears to the primary and secondary annuitant.
Benefits payable on Death
Option 1 – On the death of the annuitant during Deferment period – Death benefit to Nominee as per the option exercised by the Annuitant. On the death after deferment period no payment shall be made.
Option 2 –
During the Deferment Period – On first death of either of the covered Life – No payment. On death of the last survivor – Death benefit to Nominee as per option exercise by annuitant.
After Deferment Period – On first death of either of the covered Life – 100% of Annuity amount shall continue to be paid as long as one of the Annuitant is alive. On death of last survivor – No Annuity payment.
LIC Jeevan Shanti – Review
The positive and negative about LIC Jeevan Shanti Policy are given below.
- This plan provides new deferred Annuity option for single and joint life.
- This plan also covers Divyangjan Lives (Handicapped)
- Interest rate (Pension) increases with the increase in Deferment Period.
- Single Policy with Immediate & Deferment Annuity Type.
- First policy to have Joint Life pension option with parents and grandparents.
- Annuity increase with rate of 3% is at lower side. Inflation is increasing at much faster rate.
- This plan offers 2% discount on online purchase so, it is better to purchase online.
12 August 2018
13 May 2018
FIRST TEST RESULT DECLARED ON 13/5/2018(SECOND BATCH)
OM SAI COMPUTER CENTER,BHADRAN
(E-MAX EDUCATION)
TEST-1 MARKS OBTAINED BY STUDENTS
NAME
|
MARKS OUT OF 45 MARKS
|
%
|
JAYENDRA
|
37
|
82.22%
|
AJAY
|
34
|
75.55%
|
VILAS
|
29
|
64.44%
|
JAYESH
|
28
|
62.22%
|
JAYDIP
|
24
|
53.33%
|
MRUNALI
|
23
|
51.11%
|
NAYAN
|
20
|
44.44%
|
ROSHNI
|
13
|
28.88%
|
VIRENDRA
|
06
|
13.33%
|
AKSHAY
|
06
|
13.33%
|
AAYUSH
|
06
|
13.33%
|
1 September 2017
NATIONAL PENSION SCHEME
NPS: At a Glance
SBI National Pension System is the most economical and least known
Government approved pension scheme for Indian citizens in the 18-60 age
group. It was launched by Pension Fund Regulatory and Development
Authority (PFRDA) in 2004. The minimum yearly contribution is Rs 6,000, which either can be paid in one go or in installments of at least Rs 500.
What is National Pension Scheme?
National Pension Scheme being the
cheapest market linked retirement plan among all other Retirement plans
(EPF, PPF and Mutual Funds) suggests that it would have recorded maximum
number of sales. But due to excessively less payment of
incentive/commission to the intermediaries, it is not getting promoted
by them.
The Scenario when the scheme was
launched was worse, the fund management cost was limited at 0.0009 per
cent and points of presence, or PoPs, where investors open the account,
were not permitted to charge more than Rs 20 per account, regardless of
how big the investment was. Then there was an account opening charge of
Rs 50 for the central record-keeping agency, or CRA, in addition to an
annual CRA fee of Rs 225.
The fund management fee for
non-government funds has now increased to 0.25 per cent and for
government funds it has increased 0.0102 per cent. Also, POPs are
permitted to charge Rs.100 plus 0.25 percent of the investment. This
change will surely act as an encouragement for the agents who will now
actively market the product.
Types of National Pension Schemes (NPS):
There are two types of accounts that NPS offers:
Tier-I Account
It is a basic pension account with limitations on withdrawal
*Before attaining 60 years of
age, only 20% of the contribution can be withdrawn while the rest 80%
has to be necessarily used for buying annuity from a life insurer.
Annuity is a series of payments made at fixed intervals of time .
Annuity plans necessitate the insurer to pay the insured income at
regular intervals until his death or till maturity of the plan.
*After attaining the age of
retirement also (60 years), close to 60% contribution can be withdrawn
and the rest 40% again has to be used to purchase annuity from approved
life insurers.
Tier-II Account
It is a voluntary savings option from which a person can withdraw money limitless.
Fund Managers
The individual/organization that takes
decisions regarding any portfolio of investment (mostly a mutual fund,
pension fund, or insurance fund), as per the stated goals of the fund.
It is necessary to opt for a fund manager while opening the account.
The money is managed by seven fund managers appointed by the PFRDA. The government employees accounts are taken care of by one of the best three government fund managers, LIC Pension Plan, SBI Pension Plan and UTI Retirement Solutions, the money invested by others is managed by one of the six fund managers, ICICI Prudential Pension, IDFC Pension, Kotak Mahindra Pension, Reliance Capital Pension, SBI Pension Funds and UTI Retirement Solutions.
Mentioned below are the salient features of both Tier-I and Tier-II account
| Tier-I | Tier-II |
|---|---|
| In case of Government fund, the contribution from the employee's side is 10% basic salary + dearness allowance with exactly same contribution from the employer. | The contribution is Rs.1000 at the time of account opening or a minimum contribution of Rs.250 per month can also be chosen. Also, it is necessary to maintain a minimum balance of Rs. 2000 at the end of financial year. |
| But in non-government fund, the investor pays Rs.6000; with a choice of paying at least Rs. 500 per installment | - |
| In a Government fund, the default investment is made mostly in Corporate and Government bonds | The investment is a mix of equity, corporate bonds, government funds, FDs, liquid funds etc. |
| In a non-Government fund, the default investment is in stocks, corporate bonds, government funds, FDs, liquid funds etc. | - |
Costs Involved in National Pension Scheme
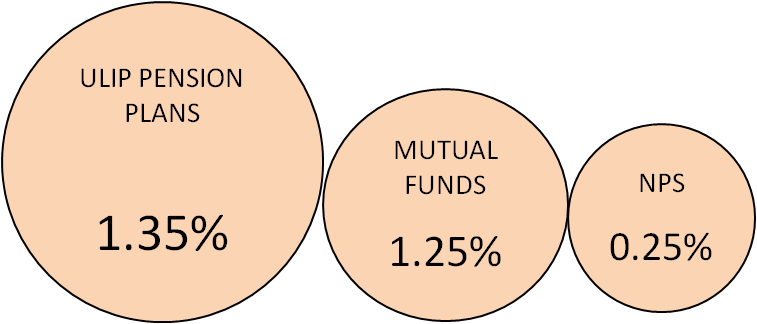
As discussed before the costs involved
are minimal, only 0.25% of the investment is paid to the intermediary as
fund management fee. Let us see how this cost is different from the
costs of the other leading pension plans.

Types of Funds in National Pension Scheme
| Class Of Fund | Invested In | Risk | Average Return Since Launch (%) |
|---|---|---|---|
|
E
|
Index based Stocks |
Carry market risk like any large cap equity fund |
3.79%
|
|
C
|
Bonds issued by State Govt, PSUs and Private Firms |
Going by the quality of companies, risk would be low. |
8.66%
|
|
G
|
Bonds issued by Central Govt. |
Lacks default risk but volatility can't be avoided in long term bonds. |
5.92%
|
Depending
on how open the investor is to risk, the corpus can be divided among
these three fund classes. Exposure to equity cannot be more than 50%.
However if the allocation is not specified, the exposure to various
classes, especially equity is decided on the basis of age.
The above figure also tells us about the average performance of National Pension Scheme funds in different classes.
The investment mix according to the age of the investor:
| Age of the Investor | Percentage of Investment in Various Classes |
|---|---|
| Up to 35 Years | 50% Equity and 50% Debt |
| 40 Years | 40% Equity and 60% Debt |
| 45 Years | 30% Equity and 70% Debt |
| 50 Years | 20% Equity and 80% Debt |
| 55 Years | 10% Equity and 90% Debt |
So with increasing age the investment corpus gets more inclined towards Debt
Pros and Cons of NPS
Pros:
Additional Tax Benefit:
The Finance Bill 2011-12 permits tax
deduction on contribution up to 10 per cent of basic salary and dearness
allowance (DA) made by an employer towards the national pension scheme (NPS) account
of an employee under Section 80CCE. This is over and above the Rs 1
lakh limit and is applicable if the contribution is done by the
employer. This is the reason why corporate houses are accepting NPS
happily.
There has been a hike in inquiries about NPS mainly because of the tax benefit under Section 80CCE.
Higher Fee to Intermediaries:
The fund management fee for
non-government funds has been raised from 0.0009 per cent of assets
under management to 0.25 per cent. The fee for government funds has been
changed to 0.0102 per cent from April this year
PoPs are allowed to charge Rs 100 plus 0.25 per cent of the investment, as against a negligible fee of Rs 20 previously.
The change is promoting New Pension Scheme by offering incentives to distributors and fund managers. The fund management fee of 0.25 per cent is nothing when compared to other products.
Cons:
Tax on Maturity Proceeds:
There is confusion about taxation at withdrawal. According to the present laws the funds would be taxed at withdrawal.
Under the current laws, around 60 per cent corpus on maturity can be withdrawn while at least 40 per cent has to be used to buy annuity. Presently, returns from annuity insurance plans are not tax-free.
The proposed Direct Taxes Code (DTC) plans to exempt NPS funds from tax at withdrawal. However, it is uncertain if the DTC would allow tax exemption on returns from annuity plans as well.
The tax at withdrawal stands in the way of making NPS the best pension scheme.
Mandatory Annuity:
Another lag is limitation on withdrawal
from Tier-I account, the primary account for pension savings. On
maturity also, one can withdraw only around 60 per cent funds; the rest
has to be used to buy annuity, the returns from which are not tax
exempted.
Even the annuity also has to be bought from one of the six PFRDA-approved insurers. Options to choose from in case of the number of annuity providers are anyway less with LIC commanding a 70 per cent market share.
Low on Equity:
NPS portfolios are restricted to have
more than 50 per cent exposure to equity. It spells loss for people in
their 20s or early 30s, as equity has shown to offer 12-15 per cent
returns per year over long periods.
In comparison to traditional retirement schemes such as EPF and Public Provident Fund, which refrain from investing in stocks at all, NPS is the best as it is a lot more flexible in terms of equity exposure.
So, investors wanting higher equity exposure can go for equity mutual fund schemes such as large-cap funds and equity exchange-traded funds.
In Comparison to its competitors; EPS and Mutual Funds, NPS leads by
*Scoring better in performance (refer to the investment mix table) and costs
*But the 40% necessary
investment in annuity after attaining the retirement age, 50% cap on
equity exposure and taxation on annuity returns does make NPS a not so
favorable option.
It is for the investor to decide as
performance and costs are good characteristics of NPS that make the
latter shine brighter than its expensive counterparts Such as Mutual
Funds.
Latest News - National Pension Schemes (NPS)
Budget 2017 Brings Relief to the Salaried Individuals Investing in NPS
Delhi, India, Feb 01:
With the release of Budget 2017, there is a relief for salaried
individuals investing in National Pension Scheme (NPS) through their
companies as they can now withdraw 25% of their handouts without paying
any tax. The Government has initiated some amendments in NPS under which
a part of withdrawal from National Pension Scheme is now Tax-free. This
initiative taken by the finance minister Mr. Arun Jaitley has brought a
major relief to the NPS subscribers.
The budget has eliminated the gap
between individual tax-paying employees and self-employed persons in
terms of income tax under section 80CCD. In order to grow the upper
limit of contribution to NPS from 10% of gross total income of a
salaried individual to 20%, the amendment of section 80CCD has been
proposed.
According to the sources, the amendment
will bring equality in tax treatment between the employee and
self-employee or non-salaried individual. The measures taken by the
government will come into action from April 1st 2018 and will be
applicable to the assessment year of 2018-2019.
22 May 2017
Pradhan Mantri Vaya Vandana Yojana Plan No. 842
Pradhan Mantri Vaya Vandana Yojana for citizens aged 60 years and above.
This LIC plan 842 will be available for sale upto 3rd May, 2018.
This is a Government subsidized pension Scheme which shall provide an assured return of 8% p.a. payable monthly (i.e. equivalent to 8.30% p.a.) on the pensioner surviving during the policy term of 10 years.
The Unique Identification Number (UIN) for "Pradhan Mantri Vaya Vandana Yojana" is 512G311V01. This number has to be quoted in all relevant documents furnished to the Policyholders and other users (public, distribution channels, etc.).
Benefits:
The benefits payable under this plan are as under:Pension Payment :
On survival of the Pensioner during the policy term, Pension in arrears (at the end of each period as per mode chosen by the Pensioner) shall be payable.Death Benefit:
On death of the Pensioner during the policy term, the Purchase Price shall be refunded to the nominee/legal heirs.Maturity Benefit:
On survival of the pensioner to the end of the policy term, Purchase price and the final pension instalment shall be payable.Eligibility Conditions and Restrictions:
Minimum Entry Age : [60] years (completed)
Maximum Entry Age : No limit
Policy Term : 10 Years
Minimum Pension : Rs. 1,000 per month / 3,000 per quarter / 6,000 per half year / 12,000 per year
Maximum Pension : Rs. 5,000 per month / 15,000 per quarter / 30,000 per half year / 60,000 per year
Ceiling of maximum pension is for a family as a whole i.e. total amount of pension under all
the policies allowed to a family under this plan shall not exceed the maximum pension limit.
The family for this purpose will comprise of pensioner, his/her spouse and dependants.
Mode of Pension Payment :
Mode of pension payment shall be monthly, quarterly, half-yearly or yearly.
The pension payment shall be through NEFT or Aadhaar Enabled Payment System.
The first instalment of pension shall be paid after 1 year, 6 months, 3 months, or 1 month from
the date of purchase of the same depending on the mode of pension payment i.e. yearly, half-
yearly, quarterly or monthly respectively.
Pension Rates:
The pension rates are not age specific and the rate of pension for Rs.1000/— purchase price fordifferent modes of pension payments are as below:
Yearly : Rs. 83.00 pa.
Half-yearly : Rs. 81.30 pa.
Quarterly : Rs. 80.50 pa.
Monthly : Rs. 80.00 p.a.
The pension instalment shall be rounded off to the nearest rupee.
Purchase Price:
The plan can be purchased by payment of a lump sum Purchase Price. The pensioner has an
option to choose either the amount of pension or the Purchase Price.
For offline sale of policies, the Purchase Price payable shall be accepted by cheques/drafts
payable on the Branch of the Bank which is member of the Local / CTS/ Speed Clearing Center.
The minimum and maximum Purchase Price under different modes of pension will be as under:
Mode of Pension Minimum Purchase Price Maximum Purchase Price
Yearly Rs. 1,44,578/— Rs. 7,22,892/—
Half-yearly Rs. 1,47,601/— Rs. 7,38,007/—
Quarterly Rs. 1,49,068/— Rs. 7,45,342/—
Monthly Rs. 1,50,000/— Rs. 7,50,000/—
The purchase price shall be rounded off to the nearest rupee.
Statutory Taxes, if any, imposed on this Plan by the Government of India or any other
constitutional tax Authority of India shall be as per the Tax laws and the rate of tax as applicable
from time to time.
The scheme allows premature exit during the policy term under exceptional circumstances like
the Pensioner requiring money for the treatment of any critical/terminal illness of self or spouse.
The Surrender Value payable in such cases shall be 98% of Purchase Price.
Loan facility is available after completion of 3 policy years. The maximum loan that can be
granted shall be 75% of the Purchase Price.
The rate of interest to be charged for loan amount would be determined from time to time by the
Corporation.
Loan interest will be recovered from pension amount payable under the policy. The Loan
interest will accrue as per the frequency of pension payment under the policy and it will be due
on the due date of pension. However, the loan outstanding shall be recovered from the claim
proceeds at the time of exit.
If a policyholder is not satisfied with the "Terms and Conditions” of the policy, he/she may return
the policy to the Corporation within 15 days (30 days if this policy is purchased online) from the
date of receipt of the policy.
The amount to be refunded within free look period shall be the Purchase Price deposited by the
policyholder after deducting the charges for Stamp duty and pension paid, if any.
this Plan.
Assignment as per section 38 of the insurance Act, 1938 as amended from time to time shall be
allowed in favour of HO of india only, if pensioner opts for loan under the policy.
Nomination by the pensioner is required as per Section 39 of the insurance Act, 1938, as
amended from time to time.
The notice of nomination or change of nomination should be submitted for registration to the
office of the Corporation, where the policy is serviced. In registering nomination the Corporation
does not accept any responsibility or express any opinion as to its validity or legal effect.
All the claim payments under this plan shall be paid through NEFT/ Aadhaar Enabled Payment
System. Other requirements are as under:
The normal documents which the claimant shall submit while lodging the claim in case of death
of the Pensioner shall be claim forms, as prescribed by the Corporation, accompanied with
original policy document, proof of title, proof of death, to the satisfaction of the Corporation. if
the age is not admitted under the policy, the proof of age of the Pensioner shall also be
submitted.
The Pensioner shall submit the Life Certificate in the proforma of the Corporation or online
“Jeevan Pramaan” as enabled by Corporation in this regard at the time intervals as prescribed
from time to time. The pension payments shall be released only on receipt of the Life Certificate.
medical treatment of self/spouse and proof of age, if the age is not admitted earlier.
proof of age, if the age is not admitted earlier.
Rebates:
No rebate (including CEIS rebate) is available under this plan.Taxes:
Statutory Taxes, if any, imposed on this Plan by the Government of India or any other
constitutional tax Authority of India shall be as per the Tax laws and the rate of tax as applicable
from time to time.
Surrender Value:
The scheme allows premature exit during the policy term under exceptional circumstances like
the Pensioner requiring money for the treatment of any critical/terminal illness of self or spouse.
The Surrender Value payable in such cases shall be 98% of Purchase Price.
Loan:
Loan facility is available after completion of 3 policy years. The maximum loan that can be
granted shall be 75% of the Purchase Price.
The rate of interest to be charged for loan amount would be determined from time to time by the
Corporation.
Loan interest will be recovered from pension amount payable under the policy. The Loan
interest will accrue as per the frequency of pension payment under the policy and it will be due
on the due date of pension. However, the loan outstanding shall be recovered from the claim
proceeds at the time of exit.
Suicide Clause:
There shall be no exclusion on count of suicide and full Purchase Price shall be payable.
Free Look Period :
If a policyholder is not satisfied with the "Terms and Conditions” of the policy, he/she may returnthe policy to the Corporation within 15 days (30 days if this policy is purchased online) from the
date of receipt of the policy.
The amount to be refunded within free look period shall be the Purchase Price deposited by the
policyholder after deducting the charges for Stamp duty and pension paid, if any.
Policy stamping :
Policy stamping charges will be at the rate of 20 paisa per thousand of Purchase Price underthis Plan.
Reinsurance:
No reinsurance is required for policies taken under this plan.
Assignments/Nominations
Assignment as per section 38 of the insurance Act, 1938 as amended from time to time shall beallowed in favour of HO of india only, if pensioner opts for loan under the policy.
Nomination by the pensioner is required as per Section 39 of the insurance Act, 1938, as
amended from time to time.
The notice of nomination or change of nomination should be submitted for registration to the
office of the Corporation, where the policy is serviced. In registering nomination the Corporation
does not accept any responsibility or express any opinion as to its validity or legal effect.
Pradhan Mantri Vaya Vandana Yojana - 842- Proposal Form
Normal requirements for claim:
All the claim payments under this plan shall be paid through NEFT/ Aadhaar Enabled Payment
System. Other requirements are as under:
For benefit payable on death of the Pensioner:
The normal documents which the claimant shall submit while lodging the claim in case of death
of the Pensioner shall be claim forms, as prescribed by the Corporation, accompanied with
original policy document, proof of title, proof of death, to the satisfaction of the Corporation. if
the age is not admitted under the policy, the proof of age of the Pensioner shall also be
submitted.
For pension payments:
The Pensioner shall submit the Life Certificate in the proforma of the Corporation or online
“Jeevan Pramaan” as enabled by Corporation in this regard at the time intervals as prescribed
from time to time. The pension payments shall be released only on receipt of the Life Certificate.
For benefit payable on Surrender:
The Pensioner shall submit the discharge form along with the original policy document, proof ofmedical treatment of self/spouse and proof of age, if the age is not admitted earlier.
For benefit payable on Maturity:
The Pensioner shall submit the discharge form along with the original policy document andproof of age, if the age is not admitted earlier.
LIC'S NEW PLAN AADHAR STAMBH
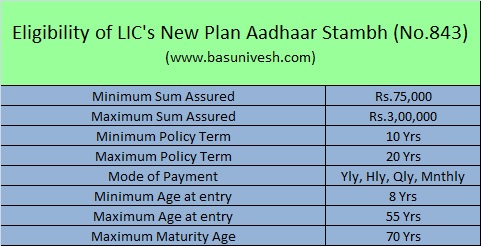
LIC’s New Plan Aadhaar Stambh (No.843) Eligibility

You notice one thing that that maximum sum assured is ONLY Rs.3,00,000.
LIC’s New Plan Aadhaar Stambh (No.843) Benefits
The benefits of LIC’s New Plan Aadhaar Stambh (No.843) are explained as below.LIC’s New Plan Aadhaar Stambh (No.843) Death Benefits
# If death occurs within first 5 yearsSum Assured on Death will be payable to the nominee. Sum Assured on Death is nothing but 110% of Basic Sum Assured. Basic Sum Assured means the sum assured you opted while buying this plan.
# If death occurs after 5th year but before maturity
Sum Assured on Death+Loyalty Addition will be payable to the nominee.
The death benefit will not be less than the 105% of all the premium paid in the policy as on date of the death of the policyholder.
Do remember that the premium paid means it will not include any taxes, extra amount charged due to underwriting decision and rider premium if any.
LIC’s New Plan Aadhaar Stambh (No.843) Maturity Benefits
Sum Assured at Maturity+Loyalty Addition. Here, Sum Assured at Maturity is equal to Basic Sum AssuredLIC’s New Plan Aadhaar Stambh (No.843) Auto Cover Benefits
When you fail to pay the insurance premium within due date, then the policy will be converted as Paid Up policy. Auto Cover Period is a period from the due date of the first unpaid period (FUP). This also includes grace period.During this Auto Cover Period, the policyholder will have the same life risk cover which he opted in the plan even though he failed to pay the premium within due dates.
The Auto Cover Period benefit available in this plan is as below.
# If at least 3 yrs but less than 5 Yrs paid but any subsequent premium is not duly paid
Auto Cover period of 6 months from the due date of the first unpaid premium will be available.
# If at least 5 Yrs premium have been paid but any subsequent premium is not paid
Auto Cover period of 2 Yrs from the due date of the first unpaid premium will be available.
LIC’s New Plan Aadhaar Stambh (No.843) other features
# You can avail loan facility after 3 years from the start of the policy.# You can revive the lapsed policy within the 2 years of first unpaid premium.
# You can opt for LIC’s Accidental Rider Benefit with this plan.
LIC’s New Plan Aadhaar Stambh (No.843) Review
As of now I have limited source of information. However, if one go by the features and benefits of this product, it is one more pathetic product from LIC. Nothing is new in this plan except they used Aadhaar as a compulsory to buy this plan and also this plan is meant only for males.Rest of the features looks like typical endowment plan with nothing much to expect than 5% to 6% returns. Also, the biggest drawback of this plan is restricting the maximum sum assured at Rs.3,00,000. However, for many of us such death claim amount may last for 1-2 years to survive. Then how can we buy such low insured product as if the life risk product which benefits our financial dependents? Strange but logically meant to encash Aadhaar based news and to trap rural population.
LIC'S NEW PLAN AADHAR SHILA
LIC’s New Plan Aadhaar Shila (No.844) is the Non-Linked (Non-ULIP),
with profits, regular premium endowment assurance plan. This means it is
not linked to stock market and we may call it as traditional endowment
type of plan.
This is the special plan for females who have Aadhaar Card. There will not be any medical examination in this plan.

You notice one thing that that maximum sum assured is ONLY Rs.3,00,000.
Sum Assured on Death will be payable to the nominee. Sum Assured on Death is nothing but 110% of Basic Sum Assured. Basic Sum Assured means the sum assured you opted while buying this plan.
# If death occurs after 5th year but before maturity
Sum Assured on Death+Loyalty Addition will be payable to the nominee.
The death benefit will not be less than the 105% of all the premium paid in the policy as on date of the death of the policyholder.
Do remember that the premium paid means it will not include any taxes, extra amount charged due to underwriting decision and rider premium if any.
During this Auto Cover Period, the policyholder will have the same life risk cover which he opted in the plan even though he failed to pay the premium within due dates.
The Auto Cover Period benefit available in this plan is as below.
# If at least 3 yrs but less than 5 Yrs paid but any subsequent premium is not duly paid
Auto Cover period of 6 months from the due date of the first unpaid premium will be available.
# If at least 5 Yrs premium have been paid but any subsequent premium is not paid
Auto Cover period of 2 Yrs from the due date of the first unpaid premium will be available.
# You can revive the lapsed policy within the 2 years of first unpaid premium.
# You can opt for LIC’s Accidental Rider Benefit with this plan.
Rest
of the features looks like typical endowment plan with nothing much to
expect than 5% to 6% returns. Also, the biggest drawback of this plan is
restricting the maximum sum assured at Rs.3,00,000. However, for many
of us such death claim amount may last for 1-2 years to survive. Then
how can we buy such low insured product as if the life risk product
which benefits our financial dependents? Strange but logically meant to
encash Aadhaar based news and to trap rural population.
This is the special plan for females who have Aadhaar Card. There will not be any medical examination in this plan.
LIC’s New Plan Aadhaar Shila (No.844) Eligibility

You notice one thing that that maximum sum assured is ONLY Rs.3,00,000.
LIC’s New Plan Aadhaar Shila (No.844) Benefits
The benefits of LIC’s New Plan Aadhaar Shila (No.844) are explained as below.LIC’s New Plan Aadhaar Shila (No.844) Death Benefits
# If death occurs within first 5 yearsSum Assured on Death will be payable to the nominee. Sum Assured on Death is nothing but 110% of Basic Sum Assured. Basic Sum Assured means the sum assured you opted while buying this plan.
# If death occurs after 5th year but before maturity
Sum Assured on Death+Loyalty Addition will be payable to the nominee.
The death benefit will not be less than the 105% of all the premium paid in the policy as on date of the death of the policyholder.
Do remember that the premium paid means it will not include any taxes, extra amount charged due to underwriting decision and rider premium if any.
LIC’s New Plan Aadhaar Shila (No.844) Maturity Benefits
Sum Assured at Maturity+Loyalty Addition. Here, Sum Assured at Maturity is equal to Basic Sum AssuredLIC’s New Plan Aadhaar Shila (No.844) Auto Cover Benefits
When you fail to pay the insurance premium within due date, then the policy will be converted as Paid Up policy. Auto Cover Period is a period from the due date of the first unpaid period (FUP). This also includes grace period.During this Auto Cover Period, the policyholder will have the same life risk cover which he opted in the plan even though he failed to pay the premium within due dates.
The Auto Cover Period benefit available in this plan is as below.
# If at least 3 yrs but less than 5 Yrs paid but any subsequent premium is not duly paid
Auto Cover period of 6 months from the due date of the first unpaid premium will be available.
# If at least 5 Yrs premium have been paid but any subsequent premium is not paid
Auto Cover period of 2 Yrs from the due date of the first unpaid premium will be available.
LIC’s New Plan Aadhaar Shila (No.844) other features
# You can avail loan facility after 3 years from the start of the policy.# You can revive the lapsed policy within the 2 years of first unpaid premium.
# You can opt for LIC’s Accidental Rider Benefit with this plan.
LIC’s New Plan Aadhaar Shila (No.844) Review
As of now I have limited source of information. However, if one go by the features and benefits of this product, it is one more pathetic product from LIC. Nothing is new in this plan except they used Aadhaar as a compulsory to buy this plan and also this plan is meant only for females.LIC'S NEW PLAN JEEVAN UMANG
LIC Jeevan Umang Plan (845) Details
LIC Jeevan Umang (Table No: 845) is a non-linked whole
life assurance plan which provides fixed yearly amount (8% of Sum
Assured/Year) after completion of premium payment up to 100 year of age
and on maturity lump sum amount on maturity (completion of 100 years) or
death. This plan is similar to Jeevan Tarang (178) Plan which is closed
for sale. Features and benefits of this plan have been explained here
with example.
Key Features
- 8% of SA per year as survival benefits
- Suitable plan for pension
- Whole Life Plan
- Availability of Accidental benefit Rider, Term Rider and Critical Illness riders.
- Paid premiums are exempted from income tax under 80C
- Maturity amount is tax free under 10 (10D)
| Calculators For Jeevan Umang Plan (845) | |
| Premium Calculator | Maturity Calculator |
Plan Parameters
| Age at Entry | 90 Days (Completed) Calculate your Age |
|---|---|
| Premium Paying Term (PPT) | 15, 20, 25, & 30 Years |
| Maximum Age at Entry in Years) (As per Nearest Birthday) |
|
| 55 for 15 PPT | |
| 50 for 20 PPT | |
| 45 for 25 PPT | |
| 40 for 30 PPT | |
| Age at Maturity | 100 Years (Nearest Birthday) |
| Policy Term | 100 - Age at Entry |
| Basic Sum Assured | 2,00,000 and above in multiples of 25,000 |
| Premium Paying Mode | Yearly, Half Yearly, Quarterly & Monthly (SSS and NACH Only) |
| Premium Payment Mode rebate | 2% on yearly, 1% on Half Yearly, Nil on Quarterly & Monthly |
Survival and Maturity Benefits
- On successful completion of premium paying term(PPT), 8% of Basic Sum Assured per year will be paid as survival benefits up to a year prior to Maturity, and
- on completion of policy term, Basic Sum Assured + Simple Reversionary Bonus +FAB will paid as maturity claim.
Death benefits
- If death happens before commencement of risk, all premiums paid excluding taxes will be paid to nominee as death claim.
- If death happens after commencement of risk, then Basic Sum Assured + Bonus + FAB will be paid to nominee as death claim.
Commencement of Risk
- In case, the policy holder is less than 8 year old, then, life cover will start 2 year after policy purchase or completion of 8 year of age, whichever is earlier. Example, if policy holder is 2 year old, then life cover (risk) will start after 2 year i.e. when policy holder will become 4 year old and if policy holder is 5 year old, then, risk will start when policy holder becomes 8 year old.
- If policy holder is 8 year old at the time of buying policy then, risk will start immediately.
To Explain the benefits associated with Jeevan Umang Policy, following example has been taken.
| Purchase Year | 2017 |
| Age (Years) | 25 (Completed) |
| Basic Sum Assured | 25,00,000 |
| Premium Paying Term | 30 |
| Policy Term | 75 (100-25) |
| Yearly Premium | 72,053 |
As per above policy details, the policy holder is require
to pay premium for 30 years and once this premium paying term of 30
years completed, the policy holder starts receiving 2,00,000 (8% of BSA)
per year up to his 99 years of age and on completion of 100 years of
age or completion of policy term maturity will be paid.
| Year No | Year | Age | Deposit Amount | Sum Assured | Bonus (Approx) | Risk Cover (Approx) | Return |
|---|---|---|---|---|---|---|---|
| 1 | 2017 | 25 | 72053 | 2500000 | 0 | 2500000 | 0 |
| 2 | 2018 | 26 | 144106 | 2500000 | 122500 | 2622500 | 0 |
| 3 | 2019 | 27 | 216159 | 2500000 | 245000 | 2745000 | 0 |
| 4 | 2020 | 28 | 288212 | 2500000 | 367500 | 2867500 | 0 |
| 5 | 2021 | 29 | 360265 | 2500000 | 490000 | 2990000 | 0 |
| 6 | 2022 | 30 | 432318 | 2500000 | 612500 | 3112500 | 0 |
| 7 | 2023 | 31 | 504371 | 2500000 | 735000 | 3235000 | 0 |
| 8 | 2024 | 32 | 576424 | 2500000 | 857500 | 3357500 | 0 |
| 9 | 2025 | 33 | 648477 | 2500000 | 980000 | 3480000 | 0 |
| 10 | 2026 | 34 | 720530 | 2500000 | 1102500 | 3602500 | 0 |
| 11 | 2027 | 35 | 792583 | 2500000 | 1225000 | 3725000 | 0 |
| 12 | 2028 | 36 | 864636 | 2500000 | 1347500 | 3847500 | 0 |
| 13 | 2029 | 37 | 936689 | 2500000 | 1470000 | 3970000 | 0 |
| 14 | 2030 | 38 | 1008742 | 2500000 | 1592500 | 4092500 | 0 |
| 15 | 2031 | 39 | 1080795 | 2500000 | 1790000 | 4290000 | 0 |
| 16 | 2032 | 40 | 1152848 | 2500000 | 1925000 | 4425000 | 0 |
| 17 | 2033 | 41 | 1224901 | 2500000 | 2072500 | 4572500 | 0 |
| 18 | 2034 | 42 | 1296954 | 2500000 | 2220000 | 4720000 | 0 |
| 19 | 2035 | 43 | 1369007 | 2500000 | 2430000 | 4930000 | 0 |
| 20 | 2036 | 44 | 1441060 | 2500000 | 2577500 | 5077500 | 0 |
| 21 | 2037 | 45 | 1513113 | 2500000 | 2825000 | 5325000 | 0 |
| 22 | 2038 | 46 | 1585166 | 2500000 | 3122500 | 5622500 | 0 |
| 23 | 2039 | 47 | 1657219 | 2500000 | 3445000 | 5945000 | 0 |
| 24 | 2040 | 48 | 1729272 | 2500000 | 3692500 | 6192500 | 0 |
| 25 | 2041 | 49 | 1801325 | 2500000 | 4065000 | 6565000 | 0 |
| 26 | 2042 | 50 | 1873378 | 2500000 | 4437500 | 6937500 | 0 |
| 27 | 2043 | 51 | 1945431 | 2500000 | 4860000 | 7360000 | 0 |
| 28 | 2044 | 52 | 2017484 | 2500000 | 5282500 | 7782500 | 0 |
| 29 | 2045 | 53 | 2089537 | 2500000 | 5705000 | 8205000 | 0 |
| 30 | 2046 | 54 | 2161590 | 2500000 | 6302500 | 8802500 | 0 |
| 31 | 2047 | 55 | 0 | 2500000 | Bonus | 8802500 + |
Subscribe to:
Posts (Atom)